

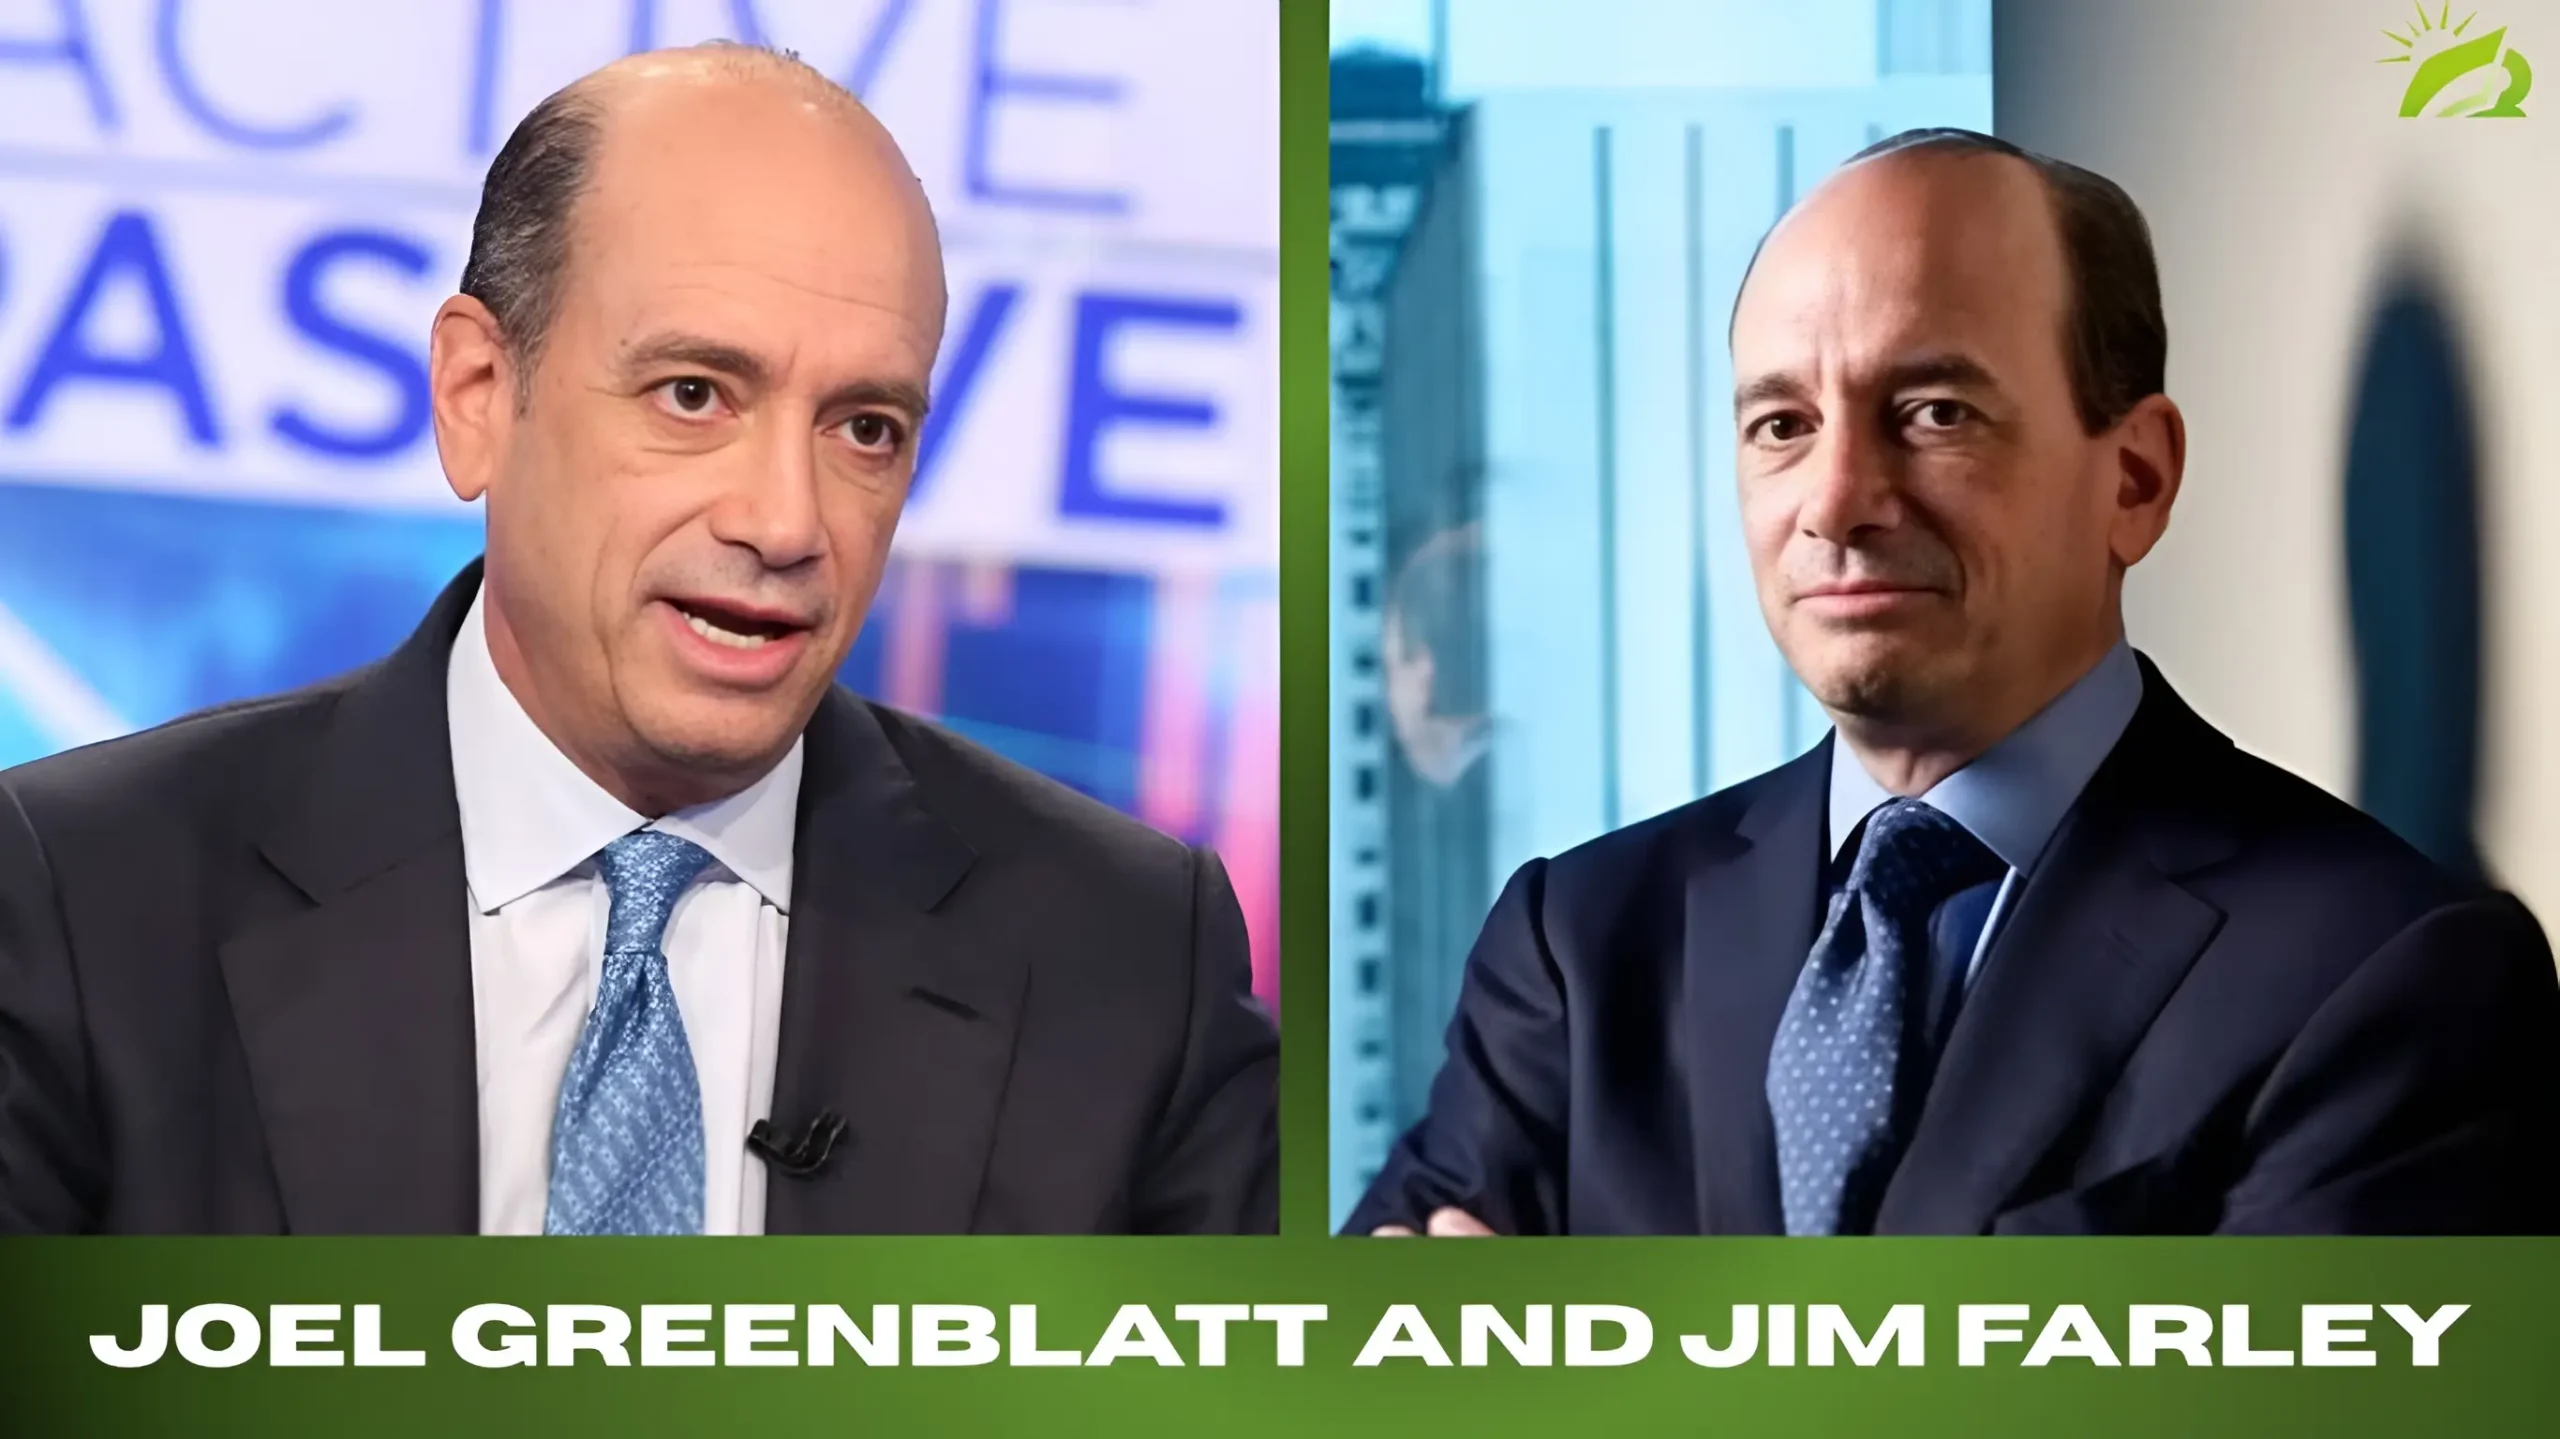
The search phrase “Joel Greenblatt and Jim Farley” brings together two professionals whose careers have developed in very different worlds. Joel Greenblatt is best known for value investing, business analysis, and his work at Gotham Asset Management, while Jim Farley is an automotive executive who serves as president and chief executive officer of Ford Motor Company.
At first glance, the two names may seem unrelated. One is associated with investing and financial research; the other is associated with vehicle design, manufacturing, branding, technology, and corporate management. Yet there is a meaningful business connection worth exploring: Gotham Asset Management, the investment firm founded by Greenblatt, has disclosed a position in Ford, while Farley has been responsible for leading Ford through a major transformation involving vehicles, software, electric mobility, commercial services, and operating efficiency.
That connection makes the topic more interesting than a simple biography of either person. It creates an opportunity to examine how an investor evaluates a business and how a chief executive attempts to improve that same business. The investor asks questions about value, returns, economics, risks, and price. The CEO must answer operational questions about products, customers, employees, technology, costs, competition, and execution.
This article explores Joel Greenblatt and Jim Farley through that broader lens. It explains who they are, why their careers are worth studying together, how Greenblatt’s investment philosophy can be used as an analytical framework for understanding companies such as Ford, and how Farley’s leadership strategy illustrates the practical side of corporate transformation.
The key point is important: there is no need to portray Greenblatt and Farley as business partners or personal collaborators when public information does not establish such a relationship. Their connection is better understood through the relationship between investment analysis and corporate leadership.
Who Is Joel Greenblatt?
Joel Greenblatt is an American investor, author, educator, and investment manager who has spent decades studying business quality, valuation, and special situations. Gotham describes itself as a value-oriented investment firm and identifies Greenblatt as its managing principal and co-chief investment officer. The company is the successor to Gotham Capital, which Greenblatt founded in 1985.
Greenblatt became particularly well known outside professional investing circles because he translated complicated financial concepts into frameworks that ordinary investors could understand. His books include You Can Be a Stock Market Genius, The Little Book That Beats the Market, The Little Book That Still Beats the Market, The Big Secret for the Small Investor, and Common Sense.
One reason his work continues to attract attention is that Greenblatt does not generally present investing as a contest of predictions. His approach places substantial emphasis on evaluating businesses using measurable financial characteristics and applying discipline when making decisions.
His best-known framework is often called the Magic Formula. At a high level, the framework combines two ideas: finding companies with attractive earnings characteristics and looking for businesses available at reasonable valuations. The attraction of that concept is its simplicity. Rather than beginning with headlines, emotions, or market excitement, the investor begins with the economics of the business.
That philosophy matters when considering Ford because Ford operates in a complex industry where a company’s story can easily dominate the underlying numbers. A new electric vehicle can generate enthusiasm. A strong truck lineup can support confidence. A manufacturing disruption can create concern. An announcement about software can change expectations. Greenblatt’s broader investing philosophy encourages an investor to step back and ask what the underlying business is actually worth.
Who Is Jim Farley?
Jim Farley is the president and CEO of Ford Motor Company. Ford’s current leadership profile says Farley is focused on transforming the company through its Ford+ strategy and describes the business as operating across vehicles, brands, software, and high-value services.
Farley’s professional background is unusually relevant to Ford’s evolution because his career has included marketing, sales, product strategy, international operations, technology, and corporate leadership.
Before joining Ford, Farley spent many years at Toyota and held senior roles connected with Lexus and Toyota marketing. Ford’s biography states that he was involved in strategic planning, product, and marketing roles before becoming group vice president and general manager of Lexus. He also played a significant role in the launch of Toyota’s Scion brand.
Farley joined Ford in 2007. He subsequently held several leadership roles, including responsibility for global markets, Lincoln, new businesses, technology, and strategy. He became Ford’s chief operating officer in 2020 and succeeded Jim Hackett as CEO later that year.
His background is significant because the modern automobile business is not simply about manufacturing vehicles. Automakers increasingly compete on software, digital services, connected features, battery technology, customer experience, manufacturing efficiency, and the strength of their underlying brands.
That means Farley’s job is much broader than selling more vehicles. He has to decide where Ford should invest, which technologies deserve resources, which businesses should receive greater attention, how costs should be controlled, and how the company can remain competitive while the automotive industry changes.
Joel Greenblatt and Jim Farley: Why Are These Names Connected?
The most useful way to understand Joel Greenblatt and Jim Farley is to separate their roles and then examine the company that connects them.
Greenblatt is an investor and investment manager. Farley is an operating executive. Greenblatt studies publicly traded businesses as potential investments. Farley manages one of the world’s major automobile companies.
The connection becomes more concrete through Gotham’s disclosed Ford position.
In its Form 13F filing covering the period ending June 30, 2026, Gotham Asset Management reported 1,434,698 shares of Ford Motor Company. Gotham identifies Greenblatt as one of its managing principals and co-chief investment officers.
That disclosure does not by itself demonstrate that Greenblatt personally selected every Ford position or that he and Farley worked together. A Form 13F is an institutional holdings disclosure, and it should be understood as a snapshot of a firm’s reportable securities rather than proof of private conversations or personal relationships.
Still, it provides an important reason the search query exists. Ford is a company associated with Jim Farley’s leadership, while Ford securities have appeared in Gotham’s reported holdings.
That creates a natural analytical question:
What might make an industrial company like Ford relevant to an investor whose philosophy emphasizes value, quality, and disciplined analysis?
Answering that question requires looking beyond celebrity or executive reputation.
The Difference Between an Investor and a CEO
The relationship between an investor and a CEO is fundamentally different from a partnership between two executives.
An investor looks at the company from the outside. A CEO operates it from the inside.
The investor is concerned with questions such as:
- How profitable is the business?
- How much capital does the business require?
- What kind of returns can it generate?
- How durable are those returns?
- What risks could damage future earnings?
- What price is being paid for those earnings?
- Is the market expecting too much or too little?
The CEO faces another set of questions:
- Which products should be developed?
- Which factories should receive investment?
- How should engineering resources be allocated?
- How can quality improve?
- How should software become part of the customer experience?
- Which customers are most valuable?
- How can manufacturing costs be reduced?
- How should the company respond to competitors?
Those questions overlap around one central concept: value creation.
An investor tries to identify value that the market may not fully recognize. A CEO tries to create value that customers and shareholders can ultimately recognize.
That is where Joel Greenblatt and Jim Farley become a useful case study.
Greenblatt’s Investment Philosophy in Simple Terms
Greenblatt’s investing philosophy is often presented as mathematical, but its practical implications are easier to understand.
Imagine two companies.
Company A produces substantial profits but requires enormous amounts of capital to maintain its operations.
Company B produces similar profits with less capital and a stronger economic position.
All else equal, the second business may have more attractive economics.
Now imagine that investors are excited about Company A and willing to pay an extremely high price for its earnings, while Company B receives little attention and trades at a lower valuation.
A disciplined value investor may become more interested in Company B.
This concept is central to Greenblatt’s approach: business quality and price both matter.
A great company can be a poor investment when purchased at an excessive valuation. Likewise, a cheap company can be a poor investment if its economics are permanently deteriorating.
That distinction is especially important in cyclical industries such as automobiles.
Why Ford Is an Interesting Company for This Framework
Ford presents an interesting analytical challenge because it is not a simple technology company, a pure manufacturer, or a traditional consumer brand.
It combines several businesses and competitive dynamics.
Ford has historically been associated with trucks, commercial vehicles, cars, and SUVs. Under Farley, the company has also developed a business structure covering Ford Blue, Ford Model e, and Ford Pro. Ford describes Ford Blue as focused on gas and hybrid vehicles, Ford Model e as its electric-vehicle and digital technology business, and Ford Pro as the commercial-focused operation serving business customers with vehicles, software, and services.
This segmentation matters because an investor who looks only at the corporate headline may miss the economic differences among these businesses.
A commercial vehicle customer does not necessarily behave like a retail consumer.
A software service does not have the same economic characteristics as vehicle manufacturing.
A mature truck line does not have the same investment profile as an emerging electric platform.
Greenblatt’s style of thinking encourages investors to break a complicated business into understandable pieces rather than treating the entire company as one undifferentiated story.
Case Study 1: Ford Blue and the Question of Business Economics
The first useful case study is Ford Blue.
Ford Blue represents Ford’s traditional vehicle operations, particularly iconic gas and hybrid products. Ford has described this segment as a core part of the company’s portfolio while it develops newer technology and business models.
From a value-investing perspective, an analyst might ask several questions.
How strong are the brands?
How much customer loyalty exists?
How much pricing power does the business have?
What happens to profitability during an industry downturn?
How much capital is required to maintain competitive products?
How vulnerable is the segment to changes in fuel preferences, regulations, technology, and consumer behavior?
The point is not to declare the business good or bad.
The point is to determine what kind of economics the business has.
This is where professional investment analysis differs from casual stock commentary. A strong product launch is useful evidence, but it is only one piece of the puzzle.
A disciplined analyst wants to know whether a company can repeatedly convert competitive advantages into economic returns.
Case Study 2: Ford Pro and Recurring Business Value
Ford Pro provides another interesting case study because commercial customers can have very different purchasing behavior from individual consumers.
A business using vehicles for deliveries, construction, transportation, field service, or other commercial purposes often cares about uptime, maintenance, productivity, financing, telematics, software, and operating costs.
That creates opportunities beyond the initial vehicle sale.
Ford has emphasized commercial vehicles along with software and services as part of its Ford Pro strategy.
From an investment-analysis standpoint, this raises an important question: Can services and software make the customer relationship more valuable over time?
If a customer purchases a vehicle and then continues purchasing related services, the economics may differ from a business model based solely on one-time product transactions.
This illustrates one of the broader lessons connecting Greenblatt’s investment philosophy with Farley’s corporate strategy.
A company’s future value may depend not only on how many products it sells but on the quality of the economics surrounding each customer relationship.
Case Study 3: Ford Model e and the Problem of Attractive Growth
Electric vehicles provide perhaps the most challenging case study.
Growth can be exciting.
New technology can create enormous markets.
New products can attract significant attention.
But growth alone does not guarantee attractive economic returns.
Ford’s Model e business has been central to its effort to compete in electric vehicles and software. Ford has also acknowledged the need to improve the economics and capital efficiency of the electric-vehicle business while adjusting parts of its product and technology roadmap.
From a Greenblatt-style analytical perspective, an investor would need to distinguish between revenue growth and value creation.
A business can grow revenue rapidly and still destroy economic value if every additional dollar of revenue requires too much investment or produces inadequate margins.
That distinction is one of the most important lessons in modern investing.
It also explains why Farley’s leadership challenge cannot be understood simply by asking whether Ford is investing in electric vehicles.
The better questions are more detailed:
How much capital is required?
How quickly can manufacturing costs improve?
Can the company reach attractive margins?
Will customers pay sufficient prices?
Can software and services improve the economics?
Can Ford develop scale advantages?
Can the company preserve its existing strengths while funding future technologies?
Those are the questions that connect corporate strategy with value-investing analysis.
Capital Allocation: The Most Important Link Between Greenblatt and Farley
Capital allocation may be the strongest conceptual link between Joel Greenblatt and Jim Farley.
For Greenblatt, investment management is fundamentally about deploying capital where expected risk-adjusted returns are attractive.
For Farley, capital allocation means deciding where Ford should place its enormous organizational and financial resources.
A CEO has only a limited amount of capital, engineering capacity, factory capacity, management attention, and employee time.
Every strategic choice comes with an opportunity cost.
Investing more heavily in electric vehicles may mean fewer resources for another project.
Expanding software capabilities may require significant upfront spending before producing meaningful recurring revenue.
Improving quality can require changes to suppliers, processes, engineering, testing, and manufacturing.
Entering new markets can increase potential revenue while also increasing complexity.
This is why capital allocation is more than an accounting term.
It is the practical process of deciding what the company will become.
What Value Investors Look for in Management
Greenblatt’s investment philosophy also highlights the importance of management quality.
But management should not be judged primarily by speeches, interviews, or personality.
An investor can look at what management actually does.
Does the company allocate capital rationally?
Does management acknowledge mistakes?
Does it communicate realistic objectives?
Does it improve operating efficiency?
Does it avoid destroying shareholder value through unnecessary spending?
Does it build competitive advantages?
Does it treat acquisitions and investments with discipline?
Those are measurable or observable questions.
Farley’s tenure at Ford provides several examples of major strategic changes that can be studied through this lens.
Under his leadership, Ford reorganized its automotive business into three customer-centered business areas and positioned Ford+ around vehicles, connected technology, software, and services.
This restructuring can be analyzed without assuming that every part will succeed or fail.
The real question is whether the structure allows Ford to make better decisions.
Why Business Structure Matters
Large companies often become difficult to manage because successful legacy operations and emerging businesses require different priorities.
A mature vehicle business may prioritize manufacturing efficiency, quality, product updates, and predictable demand.
An emerging technology business may prioritize experimentation, software development, battery innovation, platform architecture, and speed.
Those cultures can conflict.
Farley’s decision to separate major parts of Ford into Ford Blue, Ford Model e, and Ford Pro was designed to give these businesses greater focus while keeping them within the broader Ford ecosystem.
An investor analyzing the company could therefore look at each segment almost as a portfolio of businesses.
That approach makes Ford’s story easier to understand.
Instead of saying:
“Is Ford a good company?”
the analyst can ask:
“What businesses does Ford own?”
“What are the economics of each?”
“Which businesses produce cash?”
“Which businesses require investment?”
“Which businesses have durable competitive advantages?”
“Which businesses could improve significantly?”
“Which risks could impair value?”
These questions are much more useful than a simple headline.
Case Study 4: Quality, Cost, and the Hidden Side of Value Creation
Quality is another major issue where corporate management and value investing intersect.
A vehicle company can have excellent brands and exciting products, but warranty expenses, recalls, production disruptions, and delayed launches can damage profitability.
Farley has publicly acknowledged the importance of improving quality at Ford, including the financial impact associated with quality problems. Contemporary reporting has documented his discussion of those challenges with investors.
From a Greenblatt-style perspective, this is a reminder that reported revenue is not enough.
A business can have attractive sales and still struggle economically because too much value leaks through poor execution.
This is why operational discipline matters.
Reducing defects can create value even when it does not produce a flashy product announcement.
Improving supply chains can create value.
Reducing manufacturing complexity can create value.
Shortening product-development cycles can create value.
Improving customer retention can create value.
For investors, those changes can ultimately matter more than temporary news coverage.
Case Study 5: China and Competitive Reality
Another important part of Farley’s leadership is Ford’s response to competitive pressure from Chinese automakers.
Farley has repeatedly discussed the competitive threat posed by Chinese vehicle companies, particularly their ability to compete on electric vehicles, technology, and cost. Recent reporting in 2026 also shows him emphasizing both competition with Chinese manufacturers and selective partnerships where Ford believes collaboration can offer strategic benefits.
This raises a classic investment question.
What happens when an industry becomes structurally more competitive?
A value investor does not simply assume that an established company will remain dominant because it has a famous brand.
Competitive advantages must be tested.
A strong brand matters only if customers continue to value it.
Scale matters only if scale produces economic benefits.
Technology matters only if customers are willing to pay for it.
Manufacturing expertise matters only if it translates into quality and efficiency.
The auto industry demonstrates why competitive advantage should always be treated as a hypothesis to be examined rather than an assumption.
Joel Greenblatt and Jim Farley: Two Different Ways of Thinking About Risk
Risk is another point of comparison.
Greenblatt approaches risk mainly as an investor.
The risk is paying too much, misunderstanding a business, overestimating its competitive advantage, or failing to account for changes in economic conditions.
Farley approaches risk as an operator.
The risks include production disruptions, product failures, technology transitions, labor challenges, supplier problems, changing consumer preferences, geopolitical developments, and competitive pressure.
Both perspectives matter.
An investor may think:
“Even if this business grows, what could permanently reduce its value?”
A CEO may think:
“What could prevent the organization from executing the strategy?”
Those are different questions about the same underlying uncertainty.
The Importance of Price in Greenblatt’s Framework
One of the easiest mistakes when discussing Joel Greenblatt is to focus entirely on business quality while ignoring valuation.
Greenblatt’s philosophy does not simply say “buy great companies.”
The price paid matters.
Consider a hypothetical example.
Suppose an established company is expected to produce $10 billion in annual earnings. Investors become extremely optimistic and bid the company’s valuation to levels that assume years of extraordinary growth.
Now imagine another company with weaker public perception but similar normalized earnings that trades at a much lower valuation.
A value investor may find the second company more interesting even though the first business appears more exciting.
This principle helps explain why a company’s stock can behave differently from its operating performance.
A company can improve operationally while its stock performs poorly because expectations were already extremely high.
The opposite can also happen.
A company can report mediocre results while its stock rises because investors expected something even worse.
That is one reason investing and business management should never be confused.
Why Investors Should Not Automatically Copy Institutional Holdings
The presence of Ford in Gotham’s reported holdings can make the Joel Greenblatt and Jim Farley keyword especially attractive to investors searching for an explanation. But there is an important lesson here.
A disclosed institutional holding is not the same thing as a recommendation.
13F filings provide information about reportable securities at a particular date. They do not reveal every aspect of an investment manager’s reasoning, timing, hedges, private investments, or future intentions. The SEC filing for Gotham’s June 30, 2026 portfolio is a snapshot of reported holdings at that period end.
Therefore, anyone researching Ford should not reduce the analysis to:
“Joel Greenblatt owns Ford, so Ford must be a good investment.”
That is not how rigorous investment research works.
A better approach is:
“Ford appeared in a Gotham filing. Why might the business have fit the firm’s investment framework at that point, and what evidence would support or challenge that thesis?”
That is a far more useful question.
What Investors Can Learn From Joel Greenblatt
Greenblatt’s career offers several transferable principles for people studying stocks and businesses.
Think in terms of businesses, not ticker symbols.
A stock represents ownership in a company. The underlying economics of the company are what ultimately matter.
Separate quality from price.
A strong business can become an expensive investment. A weak business can become a value trap.
Use evidence instead of excitement.
A popular narrative should be the beginning of research, not the conclusion.
Be patient with a disciplined process.
A rules-based investment process can appear uncomfortable when markets favor a different story.
Understand the numbers behind the story.
Revenue, earnings, capital requirements, returns, margins, and cash flow all matter.
These ideas are particularly useful when analyzing companies undergoing significant transformation.
What Investors Can Learn From Jim Farley
Farley’s career provides a different set of lessons.
The first is that large organizations must evolve without destroying their existing strengths.
Ford cannot simply abandon its historical automotive business while waiting for emerging technologies to mature. At the same time, it cannot rely entirely on its past.
The second lesson is that strategy must eventually become operational.
A company can announce a transformation, but execution requires factories, engineers, suppliers, distribution networks, software developers, dealers, customers, and financial discipline.
The third lesson is that customer behavior matters.
Automotive technology is ultimately useful only when customers adopt it.
The fourth lesson is that corporate transformation involves trade-offs.
Every technology investment competes for resources. Every new product requires capital. Every strategic choice reduces the resources available for another choice.
This is precisely why an investor’s perspective can be useful when studying an executive’s strategy.
Joel Greenblatt and Jim Farley: Investor Versus Operator
The most compelling comparison can be summarized like this:
| Area | Joel Greenblatt | Jim Farley |
|---|---|---|
| Primary role | Investor and investment manager | Corporate executive and CEO |
| Main focus | Business value and investment opportunities | Business strategy and execution |
| Core question | What is the business worth relative to its price? | How can the business become stronger and more valuable? |
| Key concerns | Valuation, returns, quality, risk | Customers, products, costs, technology, operations |
| Time horizon | Investment-dependent, often long term | Strategic and operational, extending across business cycles |
| Main tool | Financial analysis and disciplined selection | Leadership, capital allocation, organization, execution |
This is not a competition between the two approaches.
They operate at different points in the economic system.
The investor allocates capital toward businesses.
The CEO allocates corporate resources inside the business.
Both are trying to make better decisions under uncertainty.
Is There a Direct Business Relationship Between Joel Greenblatt and Jim Farley?
Publicly available information does not establish that Joel Greenblatt and Jim Farley are business partners, co-founders, or long-term personal collaborators.
The more defensible connection is through Ford.
Farley is Ford’s CEO, while Gotham Asset Management, the investment firm founded by Greenblatt and co-led by him, has reported a Ford position in its institutional holdings.
That distinction matters because online articles sometimes turn an investment connection into a stronger personal relationship than the available evidence supports.
For a high-quality article, the safest and most useful approach is to explain exactly what is known and avoid inventing meetings, friendships, interviews, partnerships, or agreements.
Why the Keyword Has Search Potential
From an SEO perspective, Joel Greenblatt and Jim Farley is an unusual keyword because it combines two recognizable names with very different professional backgrounds.
That creates several search-intent possibilities.
A reader may want to know why the names appear together.
Another person may be researching Greenblatt’s investment in Ford.
Someone else may be searching for Jim Farley’s career and leadership strategy.
An investor may be interested in Greenblatt’s approach to evaluating Ford.
A business student may simply want to understand the connection between an investor and an automotive CEO.
A well-written article can address all of these intents without repeating the exact keyword unnaturally.
The strongest strategy is not to insert the phrase into every paragraph.
Instead, the page should establish topical relevance through related concepts such as:
- Joel Greenblatt
- Jim Farley
- Ford Motor Company
- Gotham Asset Management
- value investing
- Magic Formula
- Ford+
- Ford Blue
- Ford Model e
- Ford Pro
- capital allocation
- business valuation
- corporate strategy
- automotive industry
- competitive advantage
- investment analysis
This creates a broad semantic field around the primary keyword.
How to Analyze Ford Using a Greenblatt-Inspired Framework
Readers interested in the financial side of the Joel Greenblatt and Jim Farley topic can develop a repeatable framework.
Start with business quality.
Understand which Ford businesses have durable customer demand and which rely on favorable industry conditions.
Then examine returns on capital.
Ask whether the business produces attractive returns relative to the resources required to operate it.
Next, examine earnings quality.
Are profits supported by sustainable operations, or are they heavily influenced by unusual conditions?
Then evaluate capital intensity.
Automotive manufacturing requires substantial investment, so investors should understand the relationship between spending and economic output.
After that, examine competitive advantage.
Look at brands, scale, dealer networks, engineering expertise, commercial relationships, manufacturing capabilities, software, and distribution.
Finally, consider valuation.
Even a company with significant strengths can become a difficult investment if expectations and price become disconnected from realistic future performance.
This is where Greenblatt’s influence remains particularly relevant.
A Practical Hypothetical Case Study for New Investors
Imagine an investor discovers Ford after reading about Jim Farley’s strategy.
The investor becomes excited about trucks, hybrid products, commercial vehicles, software, and future electric models.
Instead of immediately deciding that Ford is attractive, the investor builds a checklist.
Step One: Understand the Business
The investor separates Ford into major operating areas rather than evaluating the company as one business.
Step Two: Identify the Cash Generators
Which operations currently produce the strongest economic contribution?
Step Three: Identify the Investment Projects
Which parts of the business require significant spending before reaching mature economics?
Step Four: Test Management’s Strategy
Does management’s capital allocation support the stated strategy?
Step Five: Consider Competitive Pressure
Could competitors offer similar products at lower cost?
Step Six: Calculate a Conservative Value
Rather than assuming aggressive growth, the investor considers several reasonable scenarios.
Step Seven: Compare Value With Price
Only after understanding the business does the investor consider the valuation.
This hypothetical process captures an important feature of Greenblatt’s thinking: analysis should precede excitement.
Why the Automotive Industry Is Difficult for Value Investors
Cars are expensive products, manufacturing is complicated, and consumer preferences can change quickly.
The industry also has unique challenges.
Vehicle development requires substantial upfront spending.
Factories must operate at useful levels of capacity.
Supply chains can be disrupted.
Technology transitions can make previous investments less valuable.
Government policies can influence consumer demand.
Financing conditions affect purchases.
Brand reputation can take decades to build and only a short period to damage.
That means a seemingly cheap automaker can remain cheap for a long time.
This is an important concept for anyone using a value-investing framework.
A low valuation is not automatically a catalyst.
The market may be correctly recognizing a difficult business environment.
The investment thesis therefore requires more than identifying a low price.
The Role of Expectations
One of the most powerful concepts in investing is expectations.
Suppose investors expect a company to grow rapidly.
If the company grows rapidly, but not as rapidly as expected, the stock may fall.
Now consider a company that investors largely ignore.
If that company produces modestly better results than anticipated, the stock may respond positively.
This is why valuation and expectations must be considered together.
For a company such as Ford, expectations around electric vehicles, traditional trucks, commercial services, software, and profitability can change independently.
That creates a complicated valuation picture.
An investor needs to understand not only what Ford might earn but also what the current market valuation appears to assume about the future.
The Long-Term Importance of Competitive Advantage
Greenblatt’s investment principles also lead to a deeper question: What makes a business difficult to replace?
For Ford, potential sources of competitive strength include recognizable brands, manufacturing experience, extensive distribution, relationships with commercial customers, engineering capabilities, and accumulated knowledge of large-scale vehicle production.
But competitive advantages should be tested continuously.
Technology can reduce old barriers.
Customers can change preferences.
Competitors can improve products.
New entrants can reduce costs.
Supply chains can change.
Software can alter customer expectations.
A durable competitive advantage therefore requires adaptation.
This is one of the central challenges Farley faces as CEO.
Farley’s Transformation Strategy in Context
Ford describes its Ford+ plan as a strategy designed to combine iconic vehicles and brands with software, digital services, and new technologies. The company subsequently organized its automotive activities around Ford Blue, Ford Model e, and Ford Pro.
The strategy represents an attempt to create multiple engines of value rather than depend on a single source of growth.
From an investor’s perspective, this creates both potential and uncertainty.
Multiple businesses can diversify revenue and provide new growth opportunities.
But multiple businesses can also increase complexity.
The analytical challenge is determining whether the combined business is worth more than the cost and complexity required to operate it.
That question is directly aligned with the type of business analysis associated with Joel Greenblatt.
The Bigger Lesson Behind Joel Greenblatt and Jim Farley
The deeper story behind the keyword is not really about two famous names.
It is about two ways of looking at value.
Joel Greenblatt represents the perspective of the person deciding where capital should go.
Jim Farley represents the perspective of the person deciding how corporate capital should be used.
Greenblatt asks what a business can provide an investor relative to what it costs to own it.
Farley has to decide what Ford can become by allocating resources to products, technology, employees, factories, services, and customers.
Those perspectives meet in Ford.
That makes the topic useful for investors, entrepreneurs, management students, and anyone interested in understanding how companies create economic value.
Common Mistakes When Researching Joel Greenblatt and Jim Farley
One mistake is assuming that two names appearing together online must have a personal relationship.
Another is treating a hedge-fund filing as a stock recommendation.
A third is assuming that a famous CEO automatically creates a successful investment.
Another common error is focusing entirely on revenue growth without considering profitability and capital requirements.
It is also easy to confuse a strong business with a cheap stock.
Finally, investors sometimes assume that a successful historical framework guarantees future results.
Good investment principles still require current research.
Markets change.
Industries change.
Technology changes.
Competitors improve.
Companies make mistakes.
No framework eliminates uncertainty.
Frequently Asked Questions About Joel Greenblatt and Jim Farley
Q1: Are Joel Greenblatt and Jim Farley related?
A: There is no reliable public evidence establishing Joel Greenblatt and Jim Farley as relatives. Their documented connection is primarily associated with Ford and Gotham Asset Management’s disclosed investment holdings rather than a known family relationship.
Q2: Who is Joel Greenblatt?
A: Joel Greenblatt is a well-known value investor, author, and investment manager. He founded Gotham Capital in 1985 and is a managing principal and co-chief investment officer of Gotham Asset Management. He is also known for books on investing and for the investment framework commonly called the Magic Formula.
Q3: Who is Jim Farley?
A: Jim Farley is the president and CEO of Ford Motor Company. He joined Ford in 2007 after a career at Toyota and Lexus and later held several senior Ford positions before becoming CEO in 2020.
Q4: Did Joel Greenblatt invest in Ford?
A: Gotham Asset Management, the firm founded by Joel Greenblatt and co-led by him, reported a Ford Motor Company position in its June 30, 2026 Form 13F filing. The filing reported 1,434,698 Ford shares. A 13F should be understood as a periodic institutional holdings snapshot and does not by itself establish the personal investment decision-making process of an individual portfolio manager.
Q5: Does Joel Greenblatt work for Ford?
A: No. Joel Greenblatt’s professional role is with Gotham Asset Management, where he serves as managing principal and co-chief investment officer. Jim Farley is the CEO of Ford.
Q6: What is Joel Greenblatt famous for?
A: Greenblatt is particularly known for value investing, special-situation investing, investment education, and his Magic Formula framework, which focuses on combining business quality with attractive valuation characteristics.
Q7: What is Jim Farley known for?
A: Farley is known for his leadership of Ford and for his work across marketing, product strategy, global markets, technology, and corporate transformation. As CEO, he has led Ford’s Ford+ strategy and the reorganization of its automotive business into Ford Blue, Ford Model e, and Ford Pro.
Q8: What is the connection between Joel Greenblatt and Jim Farley?
A: The most concrete public connection is Ford. Jim Farley leads Ford, while Gotham Asset Management, the investment firm founded by Greenblatt, has disclosed ownership of Ford shares. Beyond that, public evidence does not establish that Greenblatt and Farley have a formal partnership or personal business relationship.
Q9: Does Greenblatt’s investment philosophy apply to Ford?
A: Greenblatt’s general principles can be used as an analytical framework for studying Ford, particularly by examining business quality, profitability, returns on capital, competitive advantages, capital requirements, and valuation. Applying that framework does not mean that Greenblatt has publicly endorsed every aspect of Ford or that the analysis constitutes a recommendation.
Q10: What can investors learn from Jim Farley’s leadership?
A: Investors can study Farley’s decisions around organizational structure, product strategy, technology investment, commercial services, and capital allocation. Ford’s transformation illustrates how management choices can affect the economics of a large industrial company over time.
Q11: Is Joel Greenblatt a good investor?
A: Joel Greenblatt is described as a well-known value investor, but the article does not directly answer whether he is a “good investor.”
Final Thoughts on Joel Greenblatt and Jim Farley
The search for Joel Greenblatt and Jim Farley becomes much more meaningful when the topic is approached through business fundamentals rather than celebrity-style comparison.
Joel Greenblatt built his reputation by studying companies as investments and emphasizing disciplined valuation. Jim Farley built his career as an automotive executive and now leads Ford through a period of technological, competitive, and organizational change.
Their connection is therefore best understood as a meeting point between capital allocation and corporate execution.
Gotham’s reported Ford position gives the keyword a concrete investment dimension, while Farley’s role gives it an operational dimension.
For readers, the most useful lesson is not to assume that an investor’s holding automatically validates a company or that an executive’s strategy automatically creates shareholder value. A stronger approach is to examine the business itself.
Study its products.
Understand its customers.
Analyze its competitive position.
Examine its capital requirements.
Evaluate management decisions.
Consider the risks.
Separate temporary developments from structural changes.
Then compare your estimate of the business’s value with the market price.
That process captures the enduring relevance of Joel Greenblatt’s approach while also providing a practical way to study Jim Farley’s leadership of Ford.
The result is a richer understanding of both names – and, more importantly, a better framework for thinking about how investors and corporate leaders approach the same fundamental challenge: how to create, preserve, and recognize long-term business value.
For More Visits: Bright Magazine
Also Read: Dan Katz Wife: Big Cat’s Wife, Marriage & Family Life
